2026年10月22日「固定金利」と「変動金利」、何が違うのか
2026年10月22日 「固定金利」と「変動金利」、何が違うのか
Fixed Rate or Variable Rate; What Is the Difference?
こんにちは。アンホーム(フォローアップ株式会社)の矢塚です。
Hello, this is Yatsuka from Anhome (Follow-Up Inc.).
■ 住宅ローンを選ぶとき、最初に出てくる選択肢
住宅ローンの手続きを進めていくと、「固定金利にするか、変動金利にするか」という選択が出てきます。金融機関や担当者から説明を受けることになりますが、その前に基本的な違いを頭に入れておくと、説明が受け取りやすくなります。
今日は「どちらを選ぶべきか」ではなく、「それぞれどういうものか」をお伝えします。
■ One of the First Choices When Setting Up a Mortgage
At some point in the mortgage process, you will be asked whether you want a fixed interest rate or a variable one. You will receive an explanation from the lender, but having a basic understanding of the difference before that conversation makes it easier to take in.
Today's post is not about which to choose it is about what each one means.
■ 固定金利とは
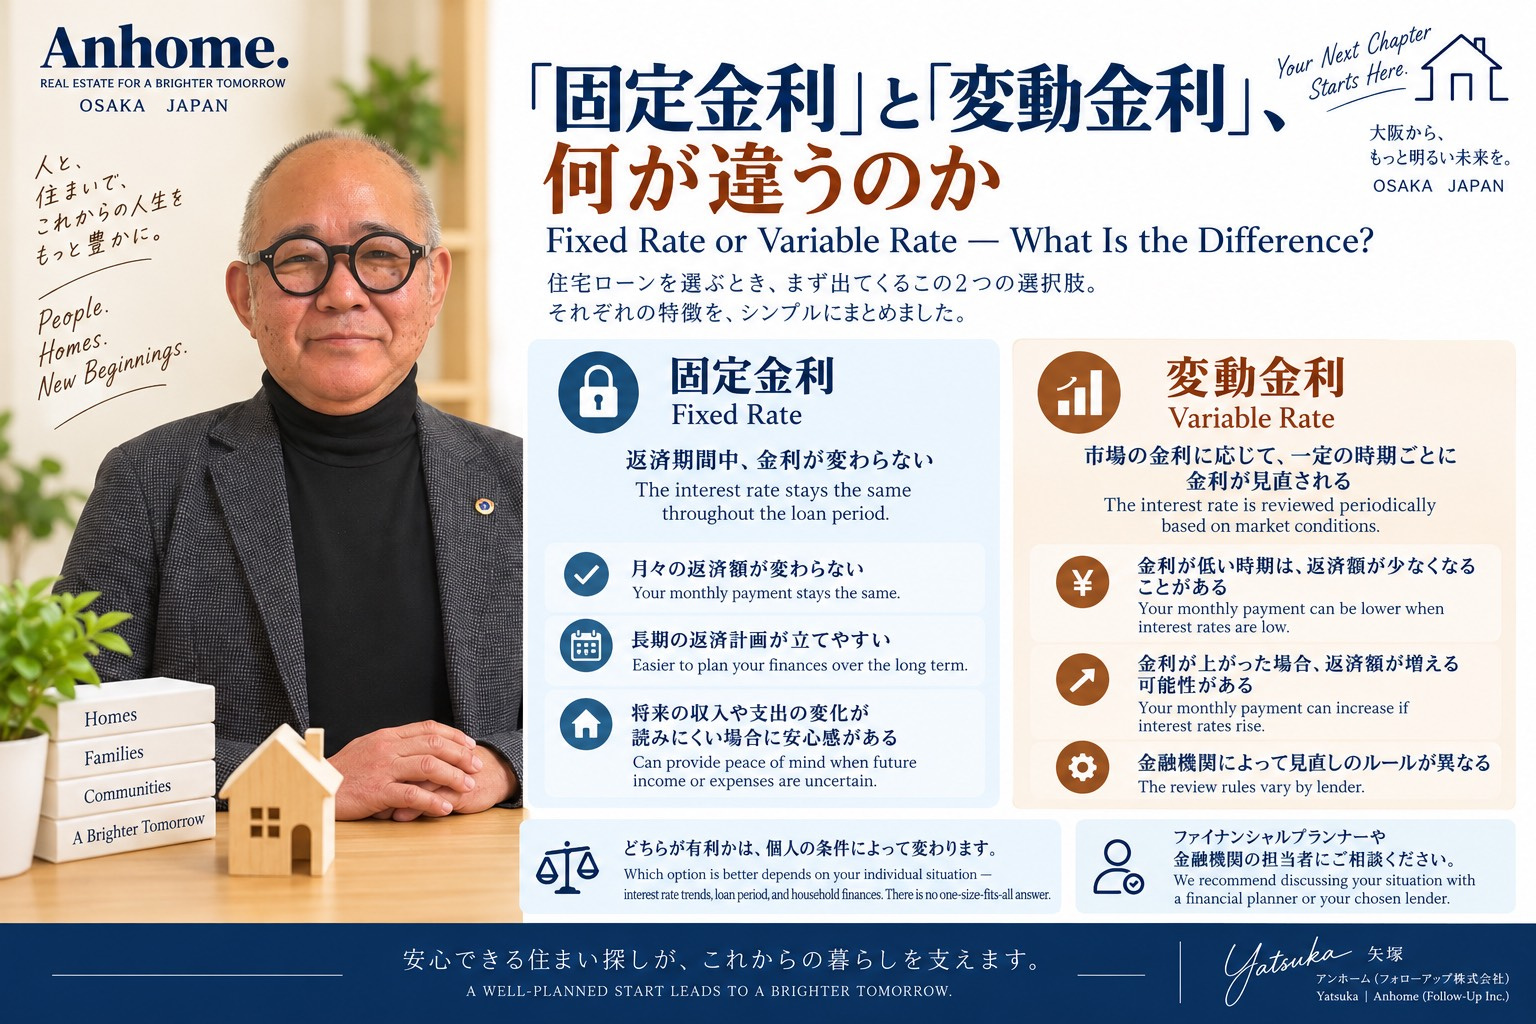
固定金利は、ローンの返済期間を通じて金利が変わらないタイプです。返済が始まった時点の金利が、完済まで続きます。
月々の返済額が変わらないため、長期間にわたる返済計画が立てやすいのが特徴です。将来の収入や支出の変化が読みにくい場合、返済額が一定であることが安心感につながることがあります。
■ What a Fixed Rate Means
With a fixed interest rate, the rate stays the same throughout the repayment period. Whatever rate applies when repayment begins continues until the loan is fully paid off.
Because the monthly payment does not change, it is easier to plan around over the long term. For households where future income or expenses are difficult to predict, knowing that the repayment amount will not shift can provide a degree of stability.
■ 変動金利とは
変動金利は、市場の金利動向に応じて、一定の時期ごとに金利が見直されるタイプです。金融機関によってルールは異なりますが、多くの場合、一定期間ごとに適用される金利が更新されます。
金利が低い時期には、固定金利より月々の返済額が少なくなることがあります。その一方で、金利が上がった場合には返済額が増える可能性があります。
■ What a Variable Rate Means
With a variable interest rate, the rate is reviewed periodically in line with market conditions. The specific rules vary by lender, but in most cases the applicable rate is updated at set intervals.
During periods when interest rates are low, the monthly payment may be lower than it would be with a fixed rate. On the other hand, if rates rise, the repayment amount can increase.
■ 両者の違いを整理すると
整理すると、固定金利は「返済額の確実性」を重視する考え方で、変動金利は「現時点での返済負担を抑える」ことを重視する考え方と言えます。どちらが有利かは、金利の動向・返済期間・家計の状況によって変わります。
一般論として「こちらが得」と言える状況は、時期によって異なります。
■ Putting the Difference in Simple Terms
In broad terms, a fixed rate prioritizes predictability in repayment, while a variable rate prioritizes keeping the repayment burden lower in the near term. Which works better depends on interest rate trends, the length of the repayment period, and the household's financial situation. There is no universal answer.
■ 判断はFP・金融機関の担当者に
どちらの金利タイプが自分の状況に合うかは、ファイナンシャルプランナーや金融機関の担当者に相談することをおすすめします。物件価格・頭金の額・返済期間・収入の安定性など、個人の条件によって判断が変わります。
私たちは不動産の売買を担当しており、住宅ローンの選択自体はお客様と金融機関の間で決まるものです。ただし、どの金融機関に相談すればいいかなど、入口の部分でお手伝いできることもあります。
■ The Choice Is Best Made With a Financial Professional
Which type of rate suits your situation is a question best discussed with a financial planner or a representative from your chosen lender. The right answer depends on individual factors: property price, down payment, repayment period, and income stability, among others.
Our role is on the real estate side of the transaction. The mortgage decision itself sits between you and your lender. That said, if you are not sure where to begin with the financial side of things, we are happy to point you in a useful direction.
■ ご相談はお気軽に
住宅購入にまつわるご質問は、金融のことも含めてまずはご相談ください。お答えできる範囲でお伝えし、必要に応じて適切な窓口をご案内します。
お電話:072-489-5661
アンホーム(フォローアップ株式会社)|大阪府知事(1)第63774号
■ Get in touch
For questions about the home-buying process, including the financial side, feel free to reach out. We will share what we can and point you in the right direction where needed.
Phone: 072-489-5661
Anhome (Follow-Up Inc.) | Osaka Prefectural Governor (1) No. 63774